
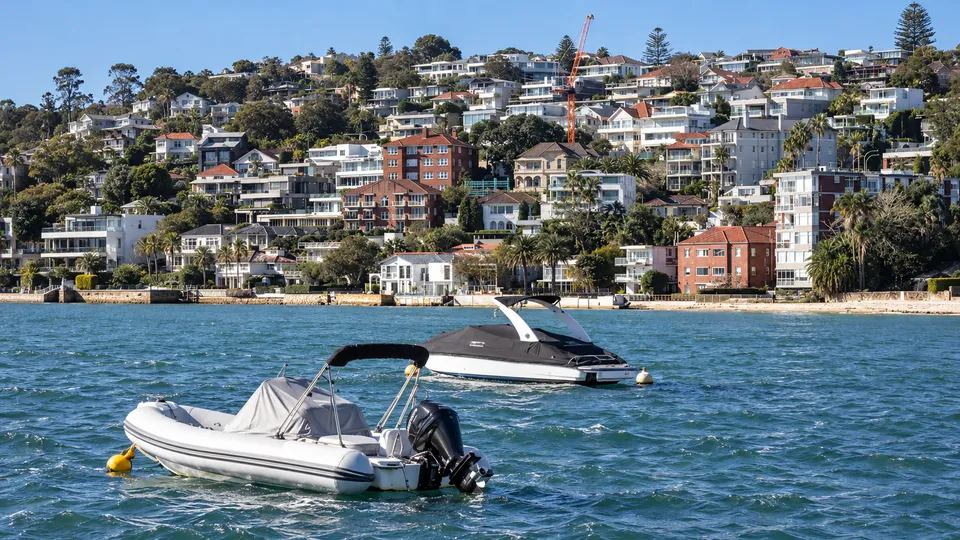
There is a widely held view in Australia that house prices only ever go up. It is less an economic forecast than a civic religion. But religions are tradeable, and one small Sydney hedge fund has decided to short this one — not by betting against houses themselves, but by betting against the website where Australians go to look at them.
As the Australian Financial Review reported, shares in property listings group REA have already fallen about 15 per cent this year to $156 on the ASX, and Bristlemoon Capital is betting they have much further to sink. The fund reckons earnings expectations will have to be cut as Australia cycles through its property downturn, and that could trigger a near 40 per cent plunge, taking the stock below $100.
Bristlemoon is a global long/short equities fund that launched in mid-2024 out of New York’s hedge-fund world. Its founder and chief investment officer, George Hadjia, a former partner at Montaka Global Investments, is the one making the case.
To understand the bet, you need to know how REA makes money. It is a toll booth. Agents and vendors pay a fee to list a property on its platform, with the price set by visual prominence, size and geographic target — the bigger the ad, the brighter the spotlight, the wider the net, the more it costs. That makes REA a play on two things at once: how many Australians are selling houses, and how much the sellers can be charged to find a buyer.
In early August the company told investors that growth in new listings in the 2027 financial year would be flat to down by low single digits, while its so-called “controllable yield” — its ability to increase revenue per listing — would grow by low double digits. That is a neat trick if you can keep doing it: volumes can sag, because prices will not.
Hadjia thinks the projections are overly optimistic. Bristlemoon expects new listing volumes to fall not by low single digits but by 5 per cent to 10 per cent in FY27. “No one can accurately predict what new listings volumes will do, but past downturns in offshore markets show that they can surprise sharply to the downside when confidence deteriorates,” he said.
And the confidence, in his telling, is going. Australian housing downturns have “typically lasted around 11 months from peak to trough”, he said, which implies prices keep falling into early 2027. “These well-heralded property price declines have shattered confidence in the market, with the widely held view that house prices in Australia only ever go up coming under increasing strain.”
Then there is the share price itself. REA trades at a price-to-earnings ratio of about 26 times, which Bristlemoon argues is a multiple for a growth company, not for a property toll booth in a downturn. Hadjia sketches a scenario in which the company’s core operating earnings fall 5 per cent in FY27 while the market reprices the stock at 20 times earnings. That gets you to $98 a share — 37 per cent below the current price. Notice, though, what even the bear case concedes: after a housing downturn, shrinking volumes and stalled pricing power, the sceptic still hands REA twenty times earnings.
Plenty of clever people are on the other side. Jun Bei Liu of Ten Cap holds a long position in REA. She agrees listing volumes will be soft, but thinks the company can offset that weakness through price increases and better products. “They are utilising AI tools and enhancing products faster than ever before,” she said. “I think REA is by far the best classifieds business compared to other ones – if we are seeing the top of the interest rate cycle, then this stock will move faster than any other.”
There is a genuinely interesting disagreement buried here about the vendor upgrade. The bull version says that in a weak market a worried seller pays for the more expensive listing package to improve the chances of a sale — hard times make premium ads worth the money. Hadjia runs the same incentive backwards: if transactions dry up and homes take longer to sell, owners may delay the expensive package until the market thaws. “This could make it harder for REA to push through large price increases during a severe downturn,” he countered. Same law of human nature, opposite signs.
What neither side in this fight disputes is the quality of the business. Liu’s bull case rests on interest rates topping out; Hadjia’s bear case rests on downturns lasting their customary 11 months. A global equities fund in Sydney is, in effect, short the proposition that Australian house prices only ever go up — historically a painful short. This one comes with a date circled for vindication: early 2027.